Africa’s Drone Indigenization Numbers Hide More Than They Show
African governments are trying to move from importing military drones to making their own. Nigeria, Ethiopia, Morocco and Kenya have long been big buyers of foreign technology for counter-terrorism, border patrol and intelligence work. The aim now is to build domestic aerospace capability as well as buy equipment, pushed by fragile supply chains and the high cost of keeping foreign hardware flying.
South Africa is still the continent’s most advanced traditional defence producer, with established aerospace engineering, but its older firms sit largely outside the venture-funded tech scene. A new wave of start-ups and state-backed facilities is moving into that gap, building AI and autonomy software into locally made drones.
One number, eight different stories
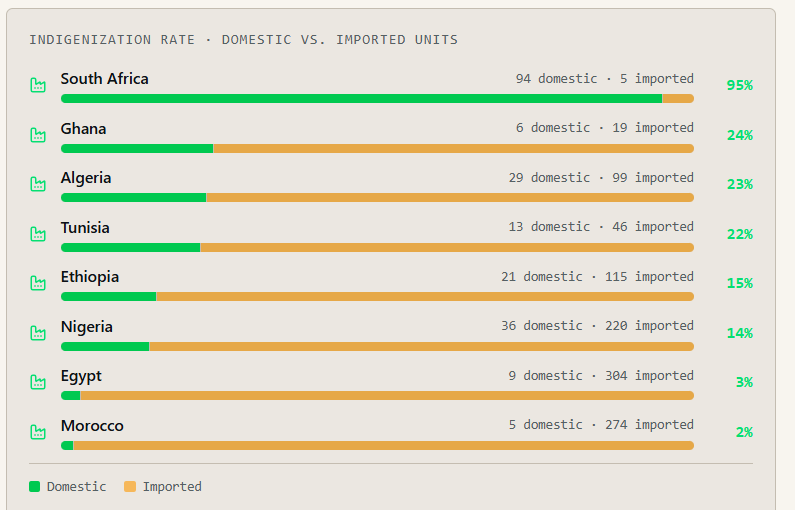
Our analysis looks at eight countries through one number that on its own says very little: the share of each military drone fleet that the country built itself. South Africa is at 95 percent. Morocco is at 2. Read in isolation, that suggests South Africa has cracked something Morocco has not even tried, and that Egypt, at 3 percent, is barely trying either. Look at what drives each figure and the picture changes. A country’s percentage often says more about how long it has been buying other people’s drones than about how seriously it is building its own.
South Africa: four decades of industry
South Africa really is different. Denel Dynamics has built reconnaissance drones since the Seeker series entered service in the late 1980s, nearly four decades of aerospace engineering that predates almost every other domestic programme on this list by a generation. Add Milkor’s 380, the largest home-designed drone flying anywhere on the continent, and South Africa’s 94 domestic units against 5 imported reflect an industrial base built over decades, not a recent policy win. That matters for reading the rest of the list, because most of the countries below it have had nowhere near that long.
Egypt and Morocco: real programmes, big import histories
Egypt and Morocco post the lowest rates here, yet both run active domestic programmes, so they are best read together. Egypt’s Ministry of Military Production and the Arab Organisation for Industrialisation have worked for years toward this, and in 2025 produced the Jabbar family, Egypt’s first fully locally designed drone line rather than a licensed or transferred design, in surveillance, target-emulation and long-range strike versions. That is a genuine step for Egyptian engineering. It is also nine units against a fleet of 313, because Egypt has imported drones at scale from the United States and elsewhere for decades, and a handful of new airframes cannot shift a total that large in a year or two.
Morocco’s case goes further. Rabat did something clever that this dataset cannot capture: it used local-content rules to make Baykar set up a production and servicing facility in Morocco before it could sell a single TB2. That brings faster maintenance, technology transfer and a local workforce learning to build drones. None of it counts as a “domestic unit” here if the aircraft leaving that line are still Turkish designs. Morocco’s 2 percent and Egypt’s 3 percent do not describe countries that have not tried. They describe import histories so large, and in Morocco’s case progress structured in a way this metric cannot see, that recent effort barely registers.
Ghana, Algeria and Tunisia: similar numbers, different routes
Ghana, Algeria and Tunisia sit close together in the low twenties, and the similarity hides how differently each got there. Ghana’s route is the most direct and, given how little attention it has had, perhaps the most impressive. The AeriusPro, a Ghanaian-designed VTOL fixed-wing hybrid that needs no runway, has been in service since around January 2026 in the Bawku and Binduri border areas, flown by the Ghana Armed Forces’ 93 Signal Regiment and linked to a locally built command-and-control system. That is six units built for Ghana’s own military, neither licensed nor assembled under a foreign brand. It is separate from the much larger factory the Nigerian start-up Terra Industries has built in Accra, which makes drones for export across the region rather than for the Ghanaian forces. Mixing the two would credit Ghana with capacity that is not its own.
Algeria’s 29 domestic units come from a longer and less certain line, the state’s Amel series, developed through several generations since 2013. Independent trackers, including the open-source monitor Oryx, judge that most Amel variants are unlikely ever to reach real service, and some of what Algeria counts as domestic production is closer to licensed local assembly of Emirati designs. Tunisia’s 13 units come from the smallest and most varied programme of the three, alongside a wider unmanned sector: the Tunisian firm ENOVA Robotics has exported ground security robots to the United States, a sign of modest but real engineering beyond aerial drones. Three countries, roughly the same number, three different routes.
Nigeria and Ethiopia: three programmes, a small percentage
Nigeria and Ethiopia sit in the middle at 14 and 15 percent, and Nigeria repeats Egypt’s pattern on a smaller scale. Nigeria is running three domestic drone efforts at once: the Air Force’s Tsaigumi from its Research and Development Centre, the venture-backed Terra Industries with its Archer and Kama lines, and Babasky Technologies’ state-partnered counter-drone system. Few African countries run that many in parallel. It still adds up to 36 units against 220 imported, because Nigeria’s imported fleet covers dozens of foreign platforms bought over years from whoever would sell: Chinese, Turkish, American and others. Three active programmes and a 14 percent rate are both true, and neither cancels the other.
Why the metric lags
The eight numbers say as much about the metric as about the countries. Measured this way, the indigenisation rate is a lagging indicator. It shows what has already been bought and built, not what is being built now or how fast. A country could be adding domestic units faster than anyone else on the continent, and if its imported fleet took thirty years to build up, its percentage would hardly move for years. The better question for each country is what is happening to the actual count of domestic units. Ghana’s went from presumably zero to six in about a year. Egypt is adding a new aircraft family rather than a few extra units. Nigeria’s is being built by three different kinds of institution at once. Those trajectories, not the percentages, will separate these eight countries five years from now.
